7 Smart Ways To Navigate Inheritance And Protect Financial Interests
Aug 22, 2026


Careful planning ensures that your assets reach the people you care about without unnecessary complications or delays. Creating a living trust allows you to bypass lengthy court processes and gives you the ability to choose who will handle important matters on your behalf. When you take time to outline your wishes and organize your documents, you help shield your loved ones from uncertainty and extra worry. Taking these clear and practical steps gives everyone peace of mind, making it easier for your family to focus on what truly matters during challenging times.
Following these steps gives you control and ease. A revocable trust adapts as your life changes, ensuring children or nieces and nephews inherit smoothly when the time comes.
Life insurance can replace lost income, cover debts or create a fund for college costs without tapping other investments. Younger adults often lock in cheaper rates, making early planning a smart move.
Family limited partnerships let you transfer ownership of businesses or property to younger generations while maintaining control. You set up the partnership, contribute assets and grant limited partner shares to children or relatives.
These partnerships offer two main benefits: valuation discounts on gifts and protection from creditors. The general partner—the one you choose—manages operations, while limited partners enjoy growth without daily responsibilities. When structured correctly, this vehicle can reduce tax burdens and keep a family venture tightly held across generations.
Gifting while alive lets you see the joy it brings. Thoughtful gifts can cover college fees, help a child buy their first home or fund a startup dream. Keeping records of amounts and recipients ensures clarity for tax time.
Health events can quickly drain savings if you haven’t set plans. A long-term care policy helps cover in-home care, assisted living or nursing facilities. Premiums may rise with age, so evaluating needs early prevents unexpected costs.
Advance medical directives specify your wishes for treatment and end-of-life care. A durable power of attorney for health care lets someone you trust make urgent decisions if you can’t. These documents protect your comfort and help loved ones understand your preferences.
Life changes, and so should your legal papers. Marriage, divorce, births and new properties all require updates. Mark a yearly date on your calendar to review your will, trust and beneficiary forms.
Digital tools can store scans of your documents, making it easier to share updates with advisors or family. Keep originals in a fireproof box at home or with a trusted attorney. Small tweaks now can prevent major headaches later.
Talk about money early and often. Host a relaxed dinner to share the basics: where key documents are, who acts as trustee and the reasoning behind your choices. Honest conversations reduce tension during changes and help younger members learn responsible handling of assets.
Invite family to attend meetings with your advisors. This step builds knowledge and trust. When everyone understands your plan, you strengthen unity and reduce misunderstandings during difficult times.
Taking these steps today sets a clear example for others to follow tomorrow. Thoughtful estate planning, including *proprietary names*, ensures your values and wishes guide future generations.
Every day, people use devices and apps to share photos, communicate, and manage tasks as simple as checking bank balances. These convenient tools often store or transmit...
Jun 02, 2026
Writing your first personal blog post feels a bit like sharing your story with a room full of new friends. Concerns about confusing settings or unexpected website...
Sep 24, 2026
Creating wealth gives you the chance to make a difference and back initiatives that matter to you. By directing your resources toward efforts such as providing clean...
Jul 24, 2026
Curiosity about cryptocurrency investing often comes with both excitement and uncertainty. You have the opportunity to discover new financial possibilities while making...
Jun 21, 2026
Setting aside a gift that grows alongside your child’s dreams gives their future a solid foundation. Planning ahead allows you to create a safety net, making higher...
Jun 15, 2026
Choosing a watch that supports your daily well-being can make a meaningful difference in your routine. A wellness-oriented smartwatch keeps track of your heart rate...
Sep 21, 2026
Learning to handle money early on gives you a real sense of control and self-reliance. Teens who get comfortable with making choices about saving, spending, and watching...
Aug 30, 2026
Warm evenings become even more enjoyable when you have a backyard that feels inviting and comfortable, almost like a natural extension of your home. Picture a place...
Jun 28, 2026
Sharing photos, videos, and thoughts on platforms such as *Instagram* and *Facebook* brings people closer and helps them discover exciting communities. Posting updates...
Sep 27, 2026
Transforming a plain wall into a warm gallery space or fixing a loose chair leg can feel simple and satisfying with the right tools on hand. When you collect a set of...
Sep 16, 2026
Sharing moments and connecting with friends on social platforms can feel exciting, yet it’s important to stay mindful of your privacy. You might enjoy posting updates,...
Aug 19, 2026
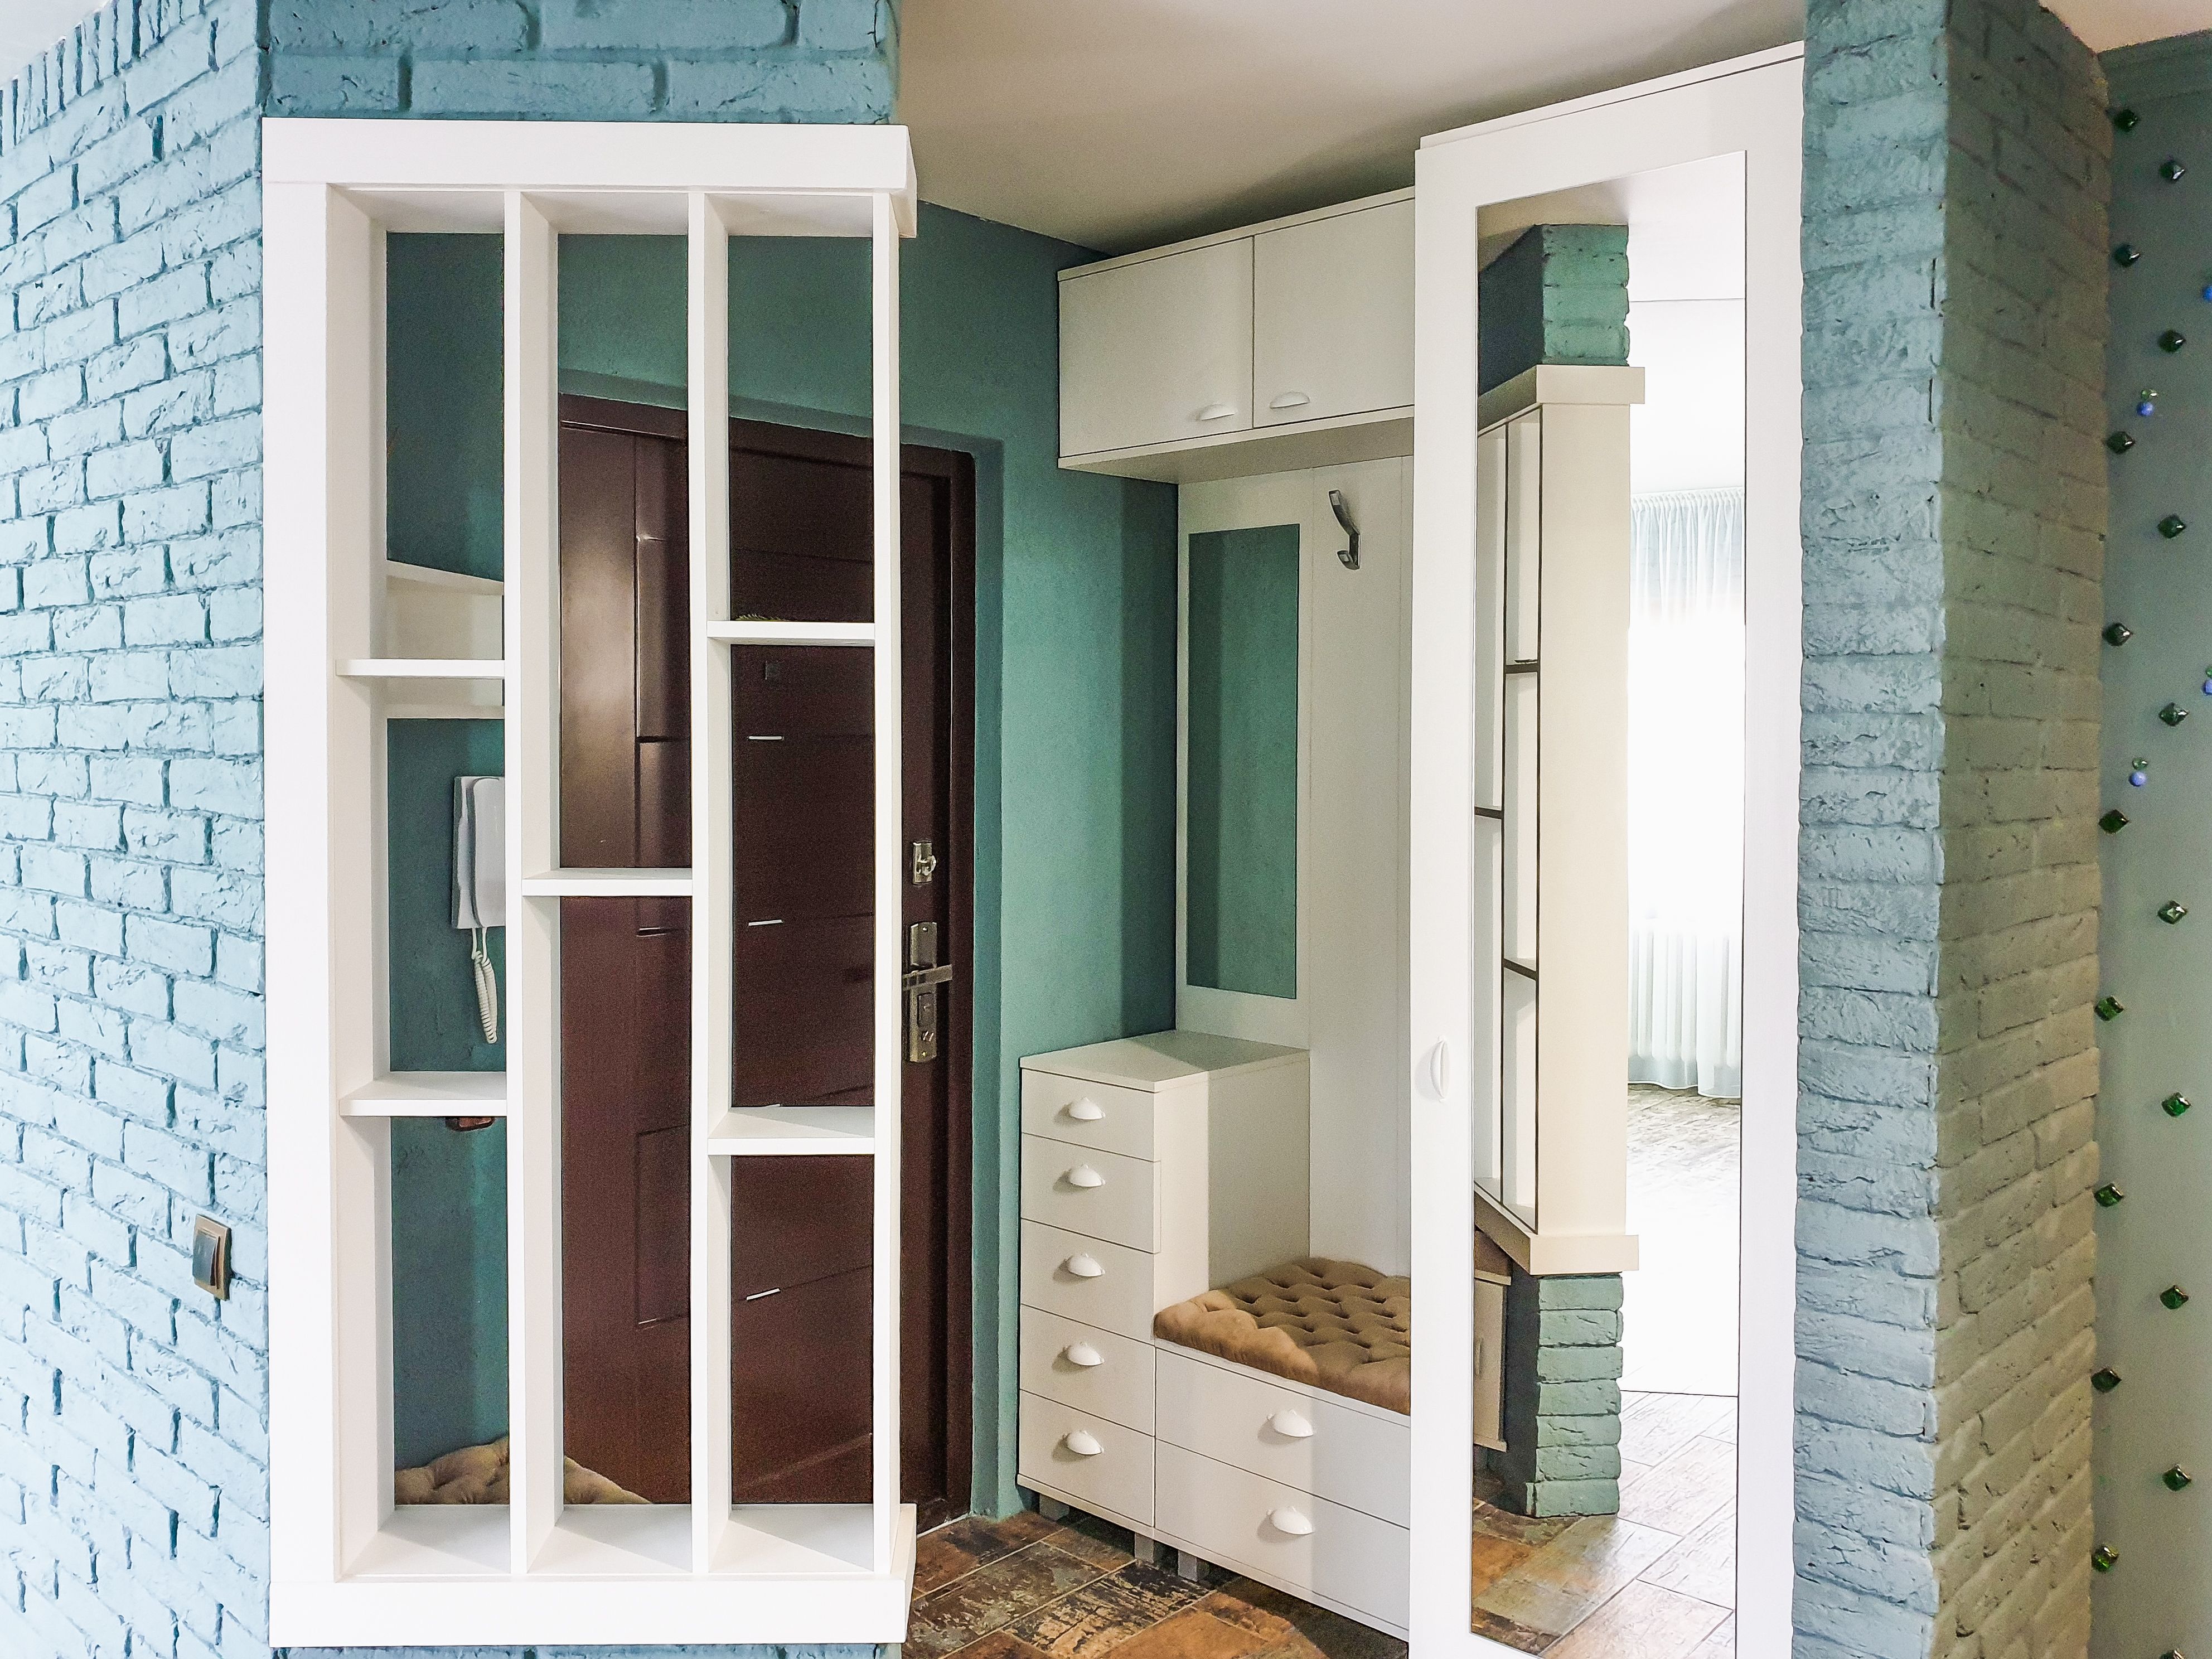
Walking through your front door can feel so much better when you’re greeted by a tidy corner that brings a sense of calm. Instead of juggling tangled keys and piles of...
Sep 12, 2026
Managing a freelance tech career involves balancing various projects, communicating with clients, and meeting tight deadlines, often from a variety of locations. Each...
Jul 10, 2026
Clutter often collects in living rooms, with toys scattered across the floor, magazines piling up on the coffee table, and blankets left draped over the couch....
Sep 04, 2026